Schedule your Complimentary Design Consultation

Furniture Financing Options Compared Before You Sign

When you compare furniture financing options, the number on the tag tells you the least about what you'll pay in the end. A monthly figure answers one question only, which is what leaves your account each month. It says nothing about the total, about the deadline that can trigger retroactive interest, or about what a returned cushion does to a schedule built around the original order.
Ask a sharper question instead. If money gets tight in month eleven, or a custom sofa lands three weeks late, what does this plan cost me then? That answer separates a tool from a trap, and most payment comparisons never get around to asking it.
Furniture Financing Options at a Glance
Which payment route fits your household budget and the way you plan to buy? The monthly payment is a starting point, not a useful comparison on its own. Look at the payment schedule, interest terms, credit requirements, and what happens if your plans change.
Six ways to pay for furniture, compared
| Option | How Payments Work | Interest Pattern | Credit Check | Best Fit |
|---|---|---|---|---|
| Retailer installment plan | Fixed monthly payments set by the lender | Stated APR from the start | Usually a credit application | Predictable payments on a larger purchase |
| Deferred-interest promotion | Pay the full balance within a set window | No interest only if paid in full by the deadline | Usually a credit application | Buyers with a firm payoff date |
| Revolving credit card | Minimum payments on an ongoing balance | Ongoing APR on unpaid balance | Credit application | Flexible timing on smaller balances |
| Personal loan | Fixed monthly payments over a set term | APR disclosed from the start | Credit application | Larger purchases needing a set schedule |
| Buy now, pay later | Several scheduled payments, often short term | Provider terms vary; late fees may apply | Often a lighter check; terms vary | Smaller orders split into a few payments |
| Saving before ordering | Pay in full before ordering | No interest | None | Buyers who want to avoid repayment obligations |
Structure determines the total repayment, so compare the mechanics before the monthly payments. Two plans can start with similar payments but produce very different totals once interest and fees are included.
A retailer installment plan and a deferred-interest promotion may look similar in an advertisement, but their payment terms work differently. An installment plan has a stated APR and fixed payments. A deferred-interest offer requires you to pay the full balance within the promotional window to avoid interest. Check the required payment against the amount you would need to pay each month to clear the balance on time.
Four more options deserve a quick look:
- Revolving credit card. Minimum payments can leave a balance outstanding, with interest charged on unpaid amounts.
- Personal loan. A fixed term and disclosed APR give you a set repayment schedule for a larger purchase.
- Buy now, pay later. These plans divide a purchase into scheduled payments, often over a shorter period. Check the provider's fees and terms.
- Saving before ordering. Paying in full avoids borrowing and scheduled repayments, though you'll need to wait until you have the full amount.
Every route has its own rules for late payments, returns, and cancellations. Read those terms before choosing, especially if the delivery date or order details could change.
If a store promotion is on your shortlist, review Indian River Furniture's current financing promotions and compare the available terms with the other payment routes.
Deferred Interest Versus True 0% Financing
A deferred-interest deadline can make a small remaining balance expensive. With true 0% promotional APR, interest is not charged during the stated period. A no-interest-if-paid-in-full offer works differently: interest may accrue from the purchase date and be charged retroactively if you miss the payoff deadline or fail to meet the offer's payment terms. The phrases describe different products with different risks.
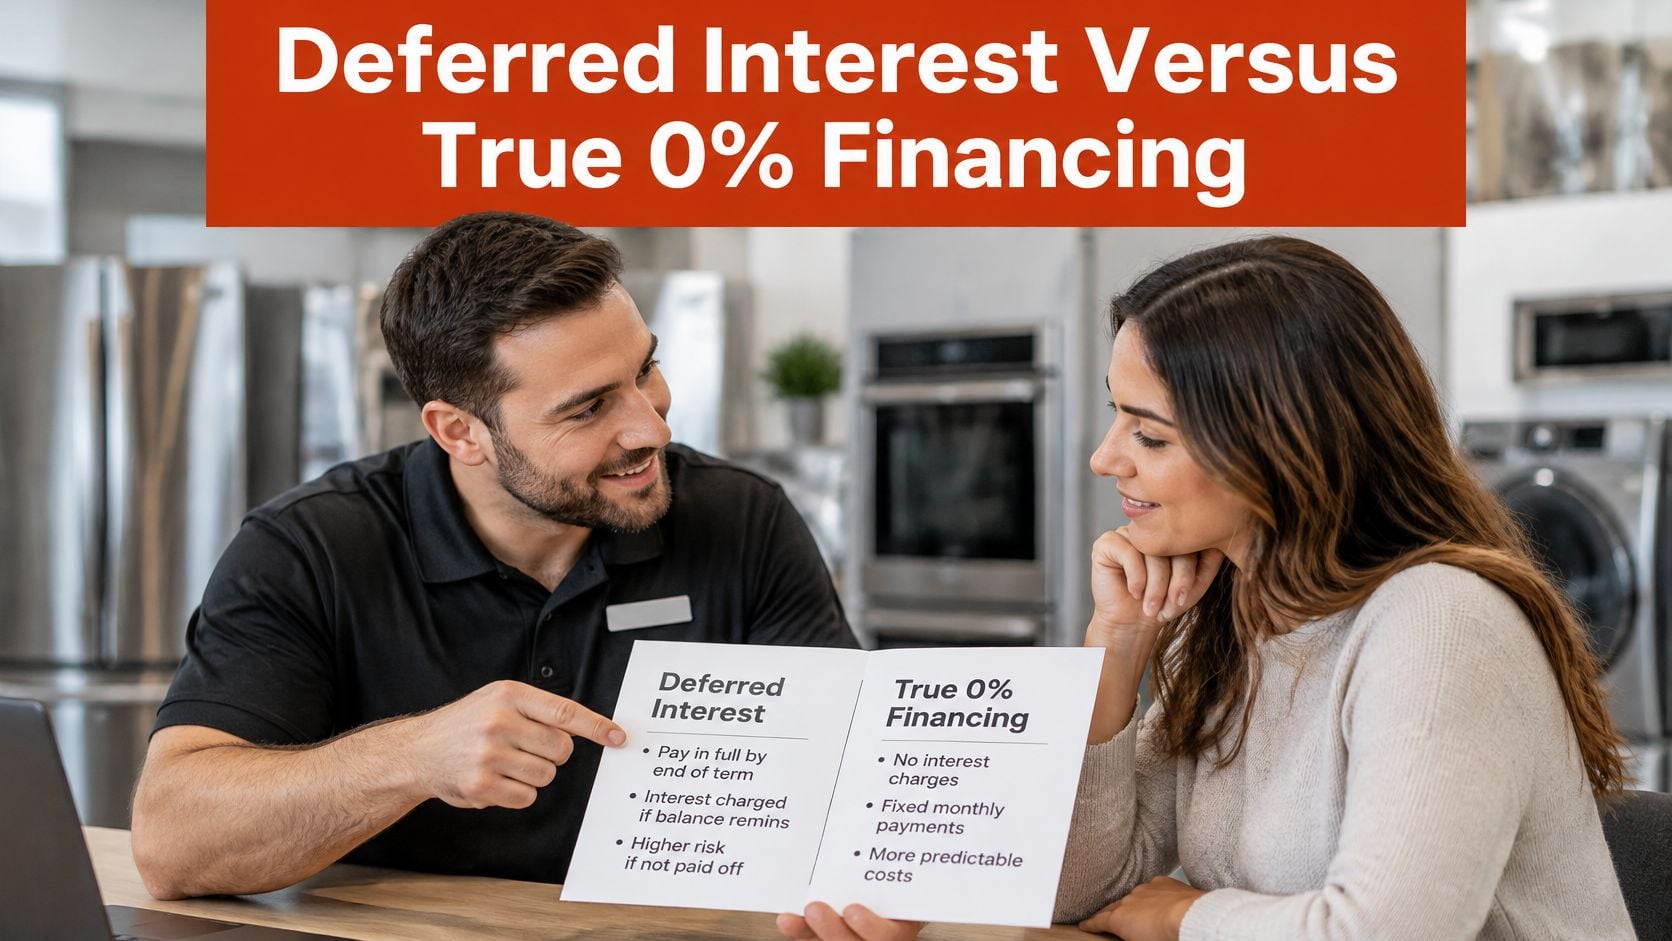
Read the regular APR and the exact payoff conditions, not just the promotional headline. The Federal Reserve's deferred-interest offer clauses explain that interest may accrue from the purchase date if the balance is not paid in full by the expiration date or a payment is late.
What a missed deferred-interest payoff can cost
| Purchase | Paid before deadline | Left unpaid | Rate | Result |
|---|---|---|---|---|
| $400 example | $300 over 12 months | $100 principal | 25% APR | About $65 accrued interest and a $165 balance |
| $4,500 furniture example | $4,320 | $180 | 31.99% APR | $1,439.55 retroactive interest |
The CFPB's $400 purchase example at 25% APR shows the effect of leaving a balance: paying $300 over twelve months leaves $100 of principal and about $65 in accrued interest, for a $165 balance when the promotion ends. The CFPB's credit card market report gives a larger illustration: after $4,320 of a $4,500 purchase is paid, the remaining $180 triggers $1,439.55 in retroactive interest at 31.99% APR.
Before signing, check five details:
- The exact payoff date. Write down the day the promotional period ends.
- The required monthly payment. Compare it with the amount needed to clear the full balance on time.
- How interest works. Confirm whether interest is waived only if you repay in full, or is never charged during the promotional period.
- Late-payment terms. Check whether a late payment can cancel the interest waiver.
- The regular APR. Know what rate applies if you miss the deadline.
The monthly payment is the least useful number if it leaves a balance at the deadline. Work out the full payoff amount and schedule before you accept the offer.
If you're considering moving existing card debt instead, the Toya AI balance transfer guide explains how 0% transfer windows work. Compare the transfer terms with the furniture offer, then choose a repayment schedule you can meet.
Financing Paths by Household Situation
A financing plan should fit the household's income pattern and the reason for buying. The useful question is which plan still works in a month when the car needs a repair.
| Household Situation | Path to Weigh First | Check Before Signing |
|---|---|---|
| Strong credit and steady income | Fixed-rate installment plan or personal loan | Total repayment and APR |
| Firm plan to clear the balance within a set window | Deferred-interest promotion | Exact payoff date and minimum monthly amount |
| Limited credit history or irregular income | Saving first or placing a smaller first order | Late-fee and credit-reporting rules |
| Urgent need for a bed or essential seating | Shortest workable installment plan | Whether a hard credit inquiry applies |
| Older adults or buyers needing lift chairs or motion seating | A plan that fits a fixed income | Delivery timing and setup |
| Whole-home or relocation furnishing | List every schedule together before choosing | Overlapping plans and combined monthly obligation |
| Custom order | Deposit plan with written terms | Cancellation and refund rules, plus lead time |
Use the middle column to narrow your options, then get the details in the right column in writing. Match the term to your timing and cash flow. A fixed-rate payment may suit steady income, while saving first or ordering fewer pieces can leave more room in a variable-income month.
Before applying, ask whether the option uses a hard credit inquiry and how the account reports payment history. Also confirm what happens if you miss a payment, return an item, or cancel part of an order. A return does not necessarily change the payment schedule automatically.
For a bed or essential seating, delivery timing matters alongside the financing terms. Buyers who need a lift chair or motion seating may have less flexibility to postpone a purchase, so choose a payment that fits the household budget without crowding out other bills. Review the furniture shopping process and planning tips to understand how an order moves from selection to delivery.
For a whole-home or relocation project, put every proposed payment schedule on one worksheet. Seeing the combined commitment makes it easier to judge whether the timing and cash flow fit.
Building a Full Repayment Plan Before You Sign
What monthly payment fits your budget through the entire promotion, including a month when expenses run high? Set a target based on the promotional period, then divide the financed principal by the number of months. For a two-year promotion, divide by 24 and plan to pay at least that amount each month. The lender's minimum may be lower, so build your schedule around the payoff deadline.
Write down every part of the purchase:
- Cash price and required down payment. Record the starting amount and what you'll pay upfront.
- Every scheduled installment. Multiply the monthly payment by the number of months and write out the full total.
- Delivery and protection costs. Include the standard $99 delivery fee and any protection plan you're considering.
- Custom-order deposits. Note what's due when you order and whether the deposit is refundable.
- Late fees and returned-payment fees. Include these potential charges in your plan.
Test the stacked plan before you total it
A sofa on one schedule, a mattress on another, and a bedroom set on a card can create a larger combined obligation than any single payment suggests. Add each monthly commitment to one worksheet, including delivery costs, and check whether the full schedule fits your income when expenses rise.
Payment allocation can affect how quickly promotional balances shrink. During the two billing cycles immediately before a deferred-interest expiration date, payments above the required minimum must generally go first to the balance subject to deferred interest, under the payment allocation rule at 12 CFR 226.53. The open-end credit rules in 12 CFR part 226, subpart G also allow issuers to follow your instructions for allocating payments above the minimum. Ask how many balances the account holds, request that extra payments go to the promotional balance, and check your next statement to confirm the allocation.
A low checkout payment can conceal a payoff schedule that stretches beyond your budget. Build the plan around the deadline and the total you can repay.
The Consumer Financial Protection Bureau reported that five major buy now, pay later providers originated about 180 million loans worth more than $24 billion in 2021, nearly ten times the 2019 volume. Its study of buy now, pay later growth also found that 73% of applicants were approved in 2021, compared with 69% in 2020, and that the share of users charged at least one late fee rose from 7.8% in 2020 to 10.5% in 2021.
Federal Reserve survey data found that 14% of U.S. adults had used buy now, pay later in the prior year by fall 2023, up from 12% in 2022 and 10% in 2021. That included 22% of adults who couldn't cover a $500 emergency expense from savings, according to the Federal Reserve survey. CFPB research found 21.2% of consumers with a credit record used buy now, pay later in 2022, up from 17.6% in 2021. Among those users, 63% held multiple simultaneous loans, 33% borrowed from more than one provider, and about 20% originated more than one loan a month, according to the CFPB research on multiple buy now, pay later loans.
Furniture deserves a full repayment check because the purchase can involve several items and charges. Add the sofa, mattress, bedroom set, and $99 delivery fee to one worksheet. A comparison of budgeting apps with free plans can help you track those commitments against your income. The reasons furniture purchases call for careful consideration make that worksheet a useful step before signing. Calculate the total repaid by the final due date. That is the room's price.
What Happens After a Missed Payment or Return
A late fee is the smaller risk. On a deferred-interest plan, one missed date can end the interest waiver and leave the full purchase balance subject to interest. A returned payment may also trigger a fee, and a late payment may be reported to credit bureaus.
Returns, partial cancellations, and delivery delays can complicate the balance. The lender may need to adjust the amount financed, but the payment schedule may not change automatically. If an order ships in separate deliveries, contact the lender and retailer promptly to confirm how the timing affects your account.
A phone call before the due date costs nothing. A dispute after it costs far more.
Five steps can keep a payment or order problem manageable:
- Set reminders a few days early. An alert before the due date gives you time to move money or contact the lender.
- Call the lender before you miss a payment. Ask whether you can change the due date while the account is current.
- Keep statements and written confirmations. Save emails or letters that document what the lender or retailer agreed to.
- Ask in writing how a return or delay changes the balance. Request the revised principal and payoff date.
- Confirm the new payoff date in writing before sending your next payment.
Set payment alerts and read the terms for order changes, returns, and cancellations before delivery. Indian River Furniture's store policies for order changes, returns, and cancellations explain how those situations are handled. For avoiding late payments with budgeting alerts, set reminders that leave time to respond before a due date.
Confirm the Piece Then Book the Visit
Bring the shortlist and the finished worksheet to the showroom, and leave the pressure at home. You're there to confirm two things: that the seat fits your body and that the terms fit your household. Neither can be settled from a photograph.
Since 1939, Indian River Furniture has served Brevard County, the Space Coast, and Central Florida. The 32,000 square foot Rockledge showroom is where that history becomes practical. Ownership hand-tests every seat, sofa, and recliner for pitch and comfort before it reaches the floor, checking lumbar support, cushion resiliency, and frame pitch. Nothing gets offered to a customer that hasn't been sat in first.
What to do in the first ten minutes
Sit for ten minutes, not ten seconds. Lean back, reach for the armrest, shift your weight toward the edge of the seat. Check where the armrest lands against your forearm and whether the cushion pushes back or gives way. Press the cushion with your palm and look at the joinery underneath, because solid wood and eight-way hand-tied springs behave differently over a decade than stapled construction does. Then feel the leathers, run a hand over the solid hardwoods, and compare cushion firmness levels side by side.
Performance fabrics for a Florida room
Humidity, salt air, sunscreen, and wet feet are the operating conditions here, and upholstery should be chosen for them. Sunbrella and Crypton performance fabrics, genuine leathers, and solid hardwood frames handle an active coastal household far better than delicate decorator cloth. The floor carries more than 1,000 performance fabrics, top-grain leathers, and custom finishes, so the material follows the room instead of the other way around.
Custom orders and the paperwork that protects you
Floor pieces can leave sooner, which matters when a guest room needs a bed this month. A custom order needs a fabric, leather, or finish decision, a deposit, and written cancellation, refund, and lead-time terms in hand before the financing agreement is signed. Ask for lead time in weeks. Confirm what happens to the financed balance if a frame arrives with a flaw, and get the delivery window in writing. Then read the payment terms once more with that delivery date beside them, because a schedule that starts before the sofa lands is a schedule you're paying while you wait.
Design help, delivery, and the flat delivery rate
Complimentary interior design consultations are included when you buy your furniture here, covering scale floor planning, fabric and finish selections, room styling, and ways to work existing heirlooms into the plan rather than around them. A scheduled appointment gives a full-room project undivided attention with swatches already pulled, and you can schedule an appointment before you drive over. If the project is one accent chair, that's a perfectly good project too. Premium white-glove delivery follows a confirmed order, with our in-house team unboxing, inspecting, and setting up the room, and deliveries run Tuesday through Saturday. The flat rate is $99 within the service area, and it belongs on the same worksheet line as the payments.
Bring the pieces you already love. A room built around an inherited chest or a grandmother's dining table outlasts one assembled from a catalog.
Three actions close the visit. Sit in the pieces until the pitch feels obvious. Confirm every financing term in writing, including the payoff date and what happens if delivery slips. Then compare total repayment against your monthly target with the $99 delivery folded in. Financing is one of the tools we offer, and that conversation is far easier in person with the sofa in front of you.
Start this week by writing the two financing structures you're seriously considering at the top of a page. Fill in the payoff date, minimum payment, and total repaid by the final due date for each, then call the Rockledge showroom and ask for a design appointment. Walk the floor, sit in three recliners and two sofas until one of them feels unmistakable, and ask the team to put the terms in writing beside the fabric swatch. If the numbers work, you'll know it. If they don't, you'll know that too, and you can wait for the right piece instead of paying monthly for the wrong one.